S&P500 Daily Action Areas & Price Targets 7/10/26
S&P500 Daily Action Areas & Price Targets 7/10/26
***QUOTING ES1!(Z CONTRACT LEVLES) FOR CASH US500 EQUIVALENT LEVELS, SUBTRACT POINT DIFFERENCE***
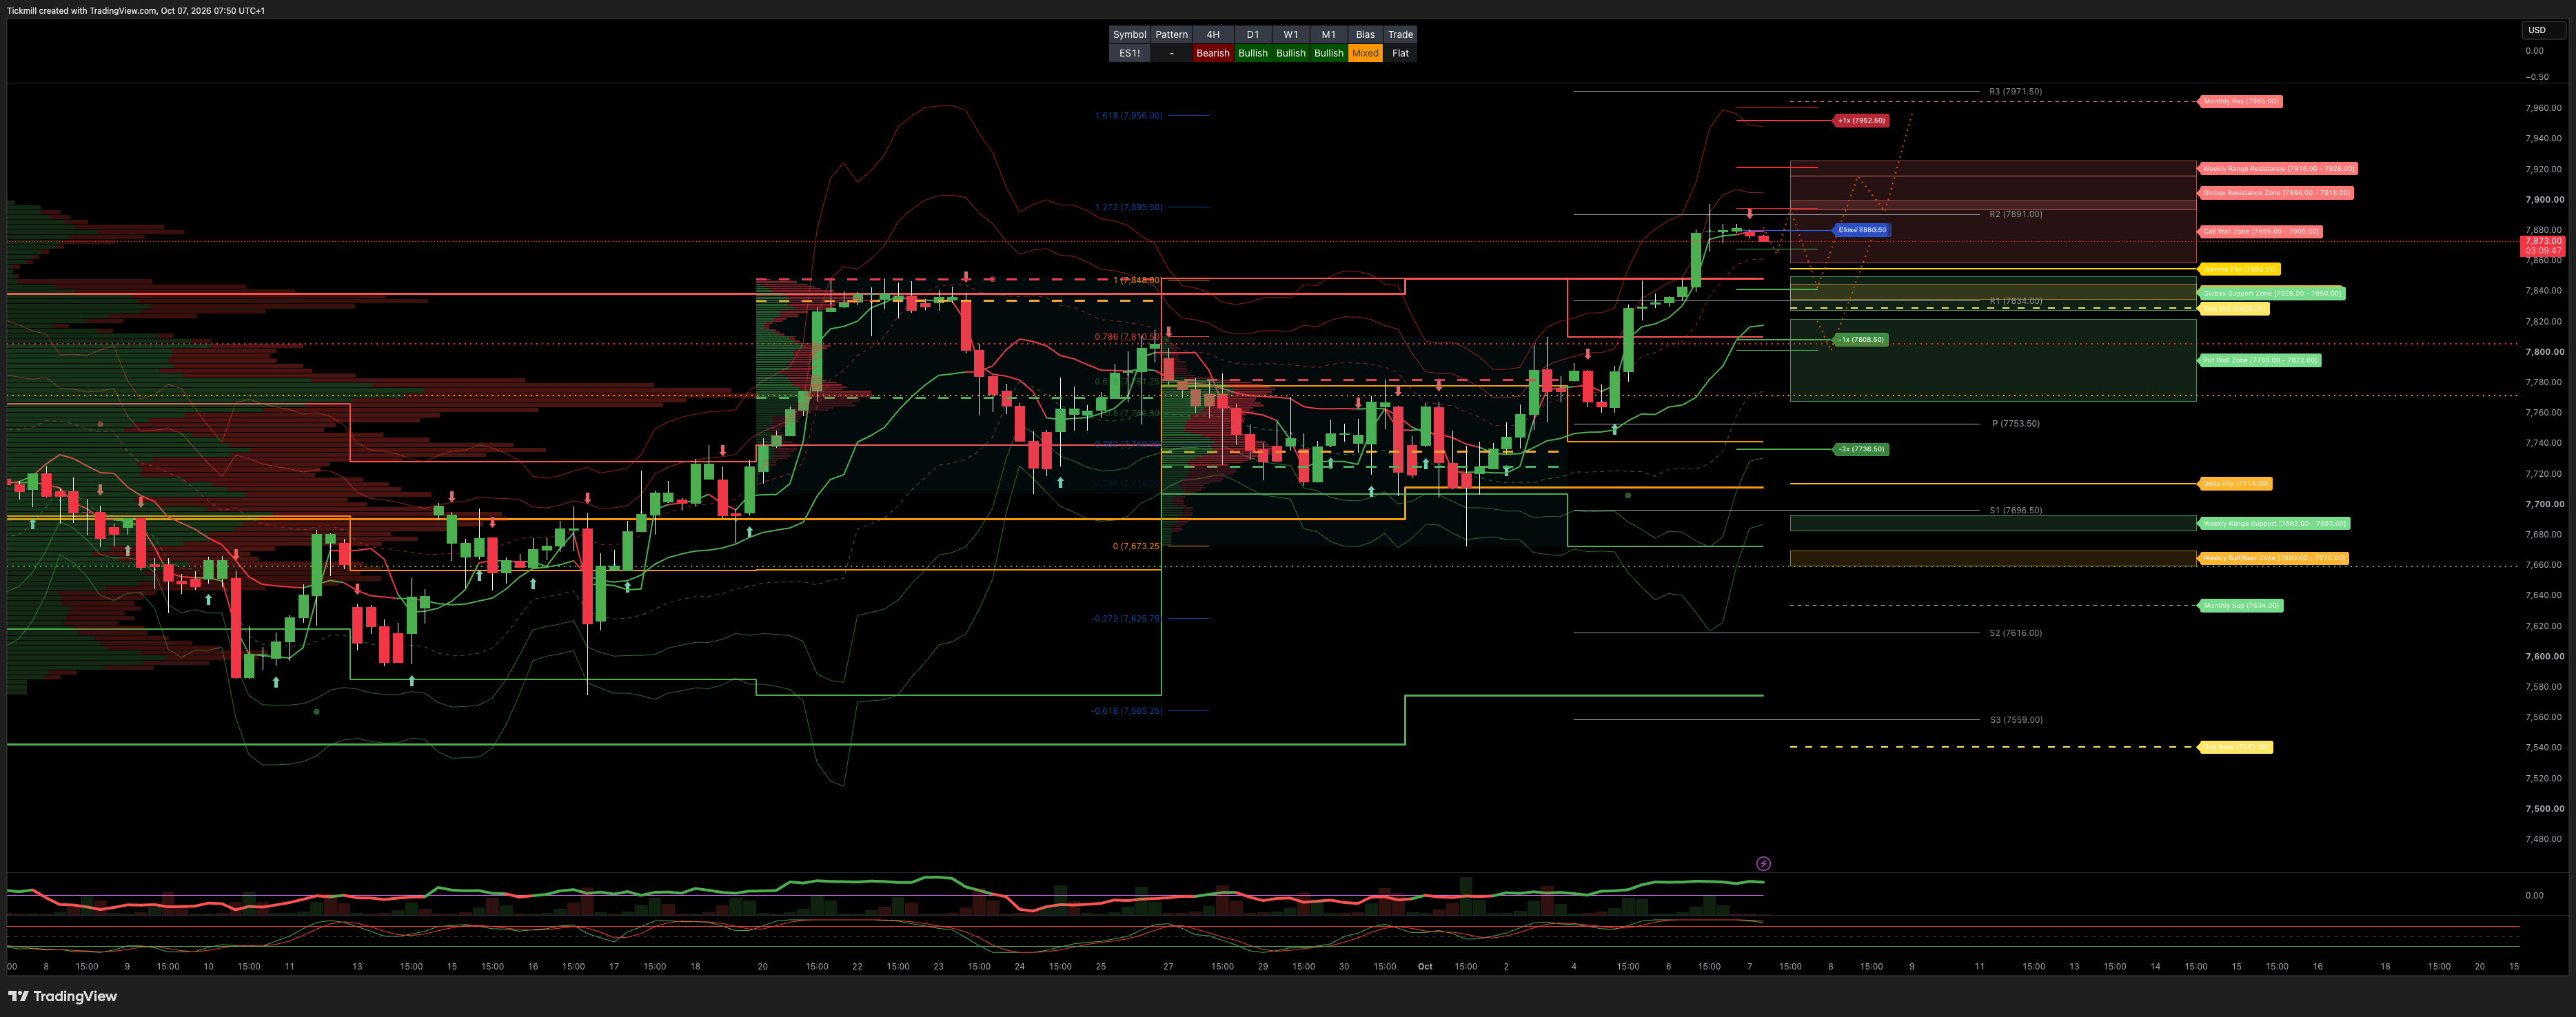
MONTHLY-WEEKLY& DAILY LEVELS
MONTHLY BULL BEAR ZONE 7440/7400
MONTHLY RANGE RES 7965 SUP 7634
WEEKLY BULL BEAR ZONE 7670/60
WEEKLY RANGE RES 7926/16 SUP 7683/93
DAILY BULL BEAR ZONE 7835/45
GLOBEX RANGE RES 7894/7916 SUP 7850/7828
GAMMA FLIP 7855
DELTA FLIP 7714
CALL WALLS 7900/7859
PUT WALLS 7822/7768
UNFILLED GAPS 7541-7829
DAILY STRUCTURE - OTFH - 7778
WEEKLY STRUCTURE - BALANCE 7848 - 7575
MONTHLY STRUCTURE - OTFH - 7542
VIX BULL BEAR ZONE 17.7
The market appears balanced, with a VVIX/VIX ratio near 5.50. Low levels in both indices suggest traders are comfortably selling options premium and expecting stable conditions to continue.
PRIMARY TRADES & TARGETS
LONG ON REJECT/RECLAIM OF THE DBBZ TARGET DAILY RANGE RES > ATH’S
***ADDITIONAL SETUPS & TARGETS HIGHLIGHTED ON THE CHARTS***
(I FADE TESTS OF 2 SIGMA LEVELS ESPECIALLY INTO THE FINAL HOUR OF THE NY CASH SESSION AS 90% OF THE TIME WHEN TESTED THE MARKET WILL CLOSE ABOVE OR BELOW THESE LEVELS)
SPX PUT/CALL RATIO 1.03 (The numbers reflect options traded during the current session.) A put-call ratio below 0.7 is generally considered bullish, and a put-call ratio above 1.0 is generally considered bearish.
JHEQX Upside cap (~7,920–7,950): Dealer gamma hedging at this call strike creates resistance, with market makers likely selling futures into strength and limiting volatility. Downside cushion (~7,270): If SPX drops 5% into Q4, long put gamma may force dealers to buy futures as the index falls, helping stabilize prices. Expiration: December 31, 2026. Strong pinning effects are likely near key strikes into year-end expiration.
DEC2025 OPEX to DEC2026 OPEX is 945 points giving us a range of [5889,7779]
Notes On Structure Implications
Balance: This refers to a market condition where prices move within a defined range, reflecting uncertainty as participants await further market-generated information. Our approach to balance includes favouring fade trades at the range extremes (highs/lows) while preparing for potential breakout scenarios if the balance shifts.
One-Time Framing Higher (OTFH): This represents a market trend where each successive bar forms a higher low, signalling a strong and consistent upward movement.
One-Time Framing Lower (OTFL): This describes a market trend where each successive bar forms a lower high, indicating a pronounced and steady downward movement.
GOLDMAN SACHS FICC & EQUITY TRADING DESK VIEWS
THE TAKE: MARKET DRIFTS HIGHER ON MACRO STABILITY AS UNDERLYING SHORT-SQUEEZE FUELS RALLY
US equity benchmarks continued their upward drift as the macro environment stabilized, supported by an overnight bid for European sovereign debt, Bessent commentary, and minor relief in crude oil and yields. The S&P 500 gained +58 bps to close at 7,818, while the Nasdaq-100 rose +48 bps to 31,224.
Under the surface, the rally remains driven by mechanical squeeze dynamics rather than aggressive fundamental buying. With fundamental Long/Short net leverage near 5-year lows (2nd percentile) and sentiment indicators at multi-year depressed levels, under-positioned institutional accounts are actively being "stopped in" to cover macro products and hedges. Simultaneously, extreme capital concentration into AI and Tech persists at the direct expense of market breadth, which remains trapped at levels not seen since 2000.
MARKET SUMMARY & ASSET BREAKDOWN
S&P 500 (SPX): Closed at 7,818.00 (+0.58%) | MOC $2.8B to SELL | VIX down -3.35% to 15.01 | Implied move through tomorrow: 39 bps
Nasdaq-100 (NDX): Closed at 31,224.00 (+0.48%) | Extended breakout gains on persistent tech concentration and short covering
Russell 2000 (RUT): Closed at 2,827.00 (-0.68%) | Clear underperformer as small-caps lagged broader index strength
Dow Jones (DJI): Closed at 51,521.00 (+0.49%) | Modest gains across industrial and value components
US 10-Year Treasury: Yield at 5.2793% (-2.5 bps) | Yields eased slightly from cycle highs
WTI Crude: Price at $89.84 (+0.46%) | Consolidated near $90/bbl
Gold: Price at $4,169.00 (+0.72%) | Bounced as the USD Index softened (DXY 101.85)
Bitcoin: Price at $85,593.00 (-0.22%) | Range-bound consolidation
CBOE VIX: Closed at 15.01 (-3.35%) | SPX fixed strike vols failed to bid despite spot realizing above straddles 3 days in a row
THEMATIC LEADERS & SINGLE-STOCK DISRUPTIONS
Power Up America Basket (
GSENEPOW+4.50%): Top-performing desk basket following Google headlines emphasizing massive AI-driven power demand. Constellation Energy (CEG +12.00%) led nuclear and utility momentum.Storage & Semicap Pressure (STX / WDC -8% to -10%): Hard Disk Drive (HDD) names faced severe selling pressure on renewed competitive concerns stemming from Toshiba expansion headlines. Weakness bled directly into semiconductor capital equipment equipment suppliers (AMAT, KLAC, LRCX).
Biotech Underperformance (XBI -3.50%): Dragged lower by AVBP (-46.00%) following a clinical trial miss, adding to recent negative news flow across the sector.
INSTITUTIONAL FLOWS & DERIVATIVES COLOR
Desk Activity (+670 bps Net Buy / 4/10 Rating):
Execution floor finished +670 bps better to buy, though overall volume remained muted.
Flow skews across both Asset Managers and Hedge Funds were better to buy, driven primarily by tech and macro product covers.
Primary Drivers of NDX Breakout:
Clean Positioning: Hedge fund net leverage approaching 5-year lows alongside multi-year low sentiment metrics.
Systematic & Macro Cover: Persistent short covering in macro products and portfolio hedges.
AI Allocation Drain: Unrelenting cash concentration into Tech/AI at the expense of broader market constituents.
Derivatives & Volatility Dynamics:
Skew Divergence: SPX skew crush persisted, whereas NDX skew steepened further along the curve.
Large SPY Option Restructuring: A major GS customer executed a $15M premium trade, selling 44k SPY Dec 800 Calls to buy 55k SPY Dec 810 Calls and 33k SPY Nov 800 Calls.
VIX & Energy Options Strategy: Desk favors VIX Call Spreads out to November (noting asset managers are historically max-short VIX futures). Desk also favors upside call structures in Nuclear / Renewable Energy (URA) given massive corporate and government deal flow.
Upcoming Micro/Macro Catalysts: FOMC Minutes, US $39B 10-Year Treasury Auction, Applied Digital (APLD) & Levi’s (LEVI) earnings, and Costco September sales.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!