FTSE Climbs to Two-Week Highs as Defence Rally Offsets Mining Drag Ahead of Inflation Data
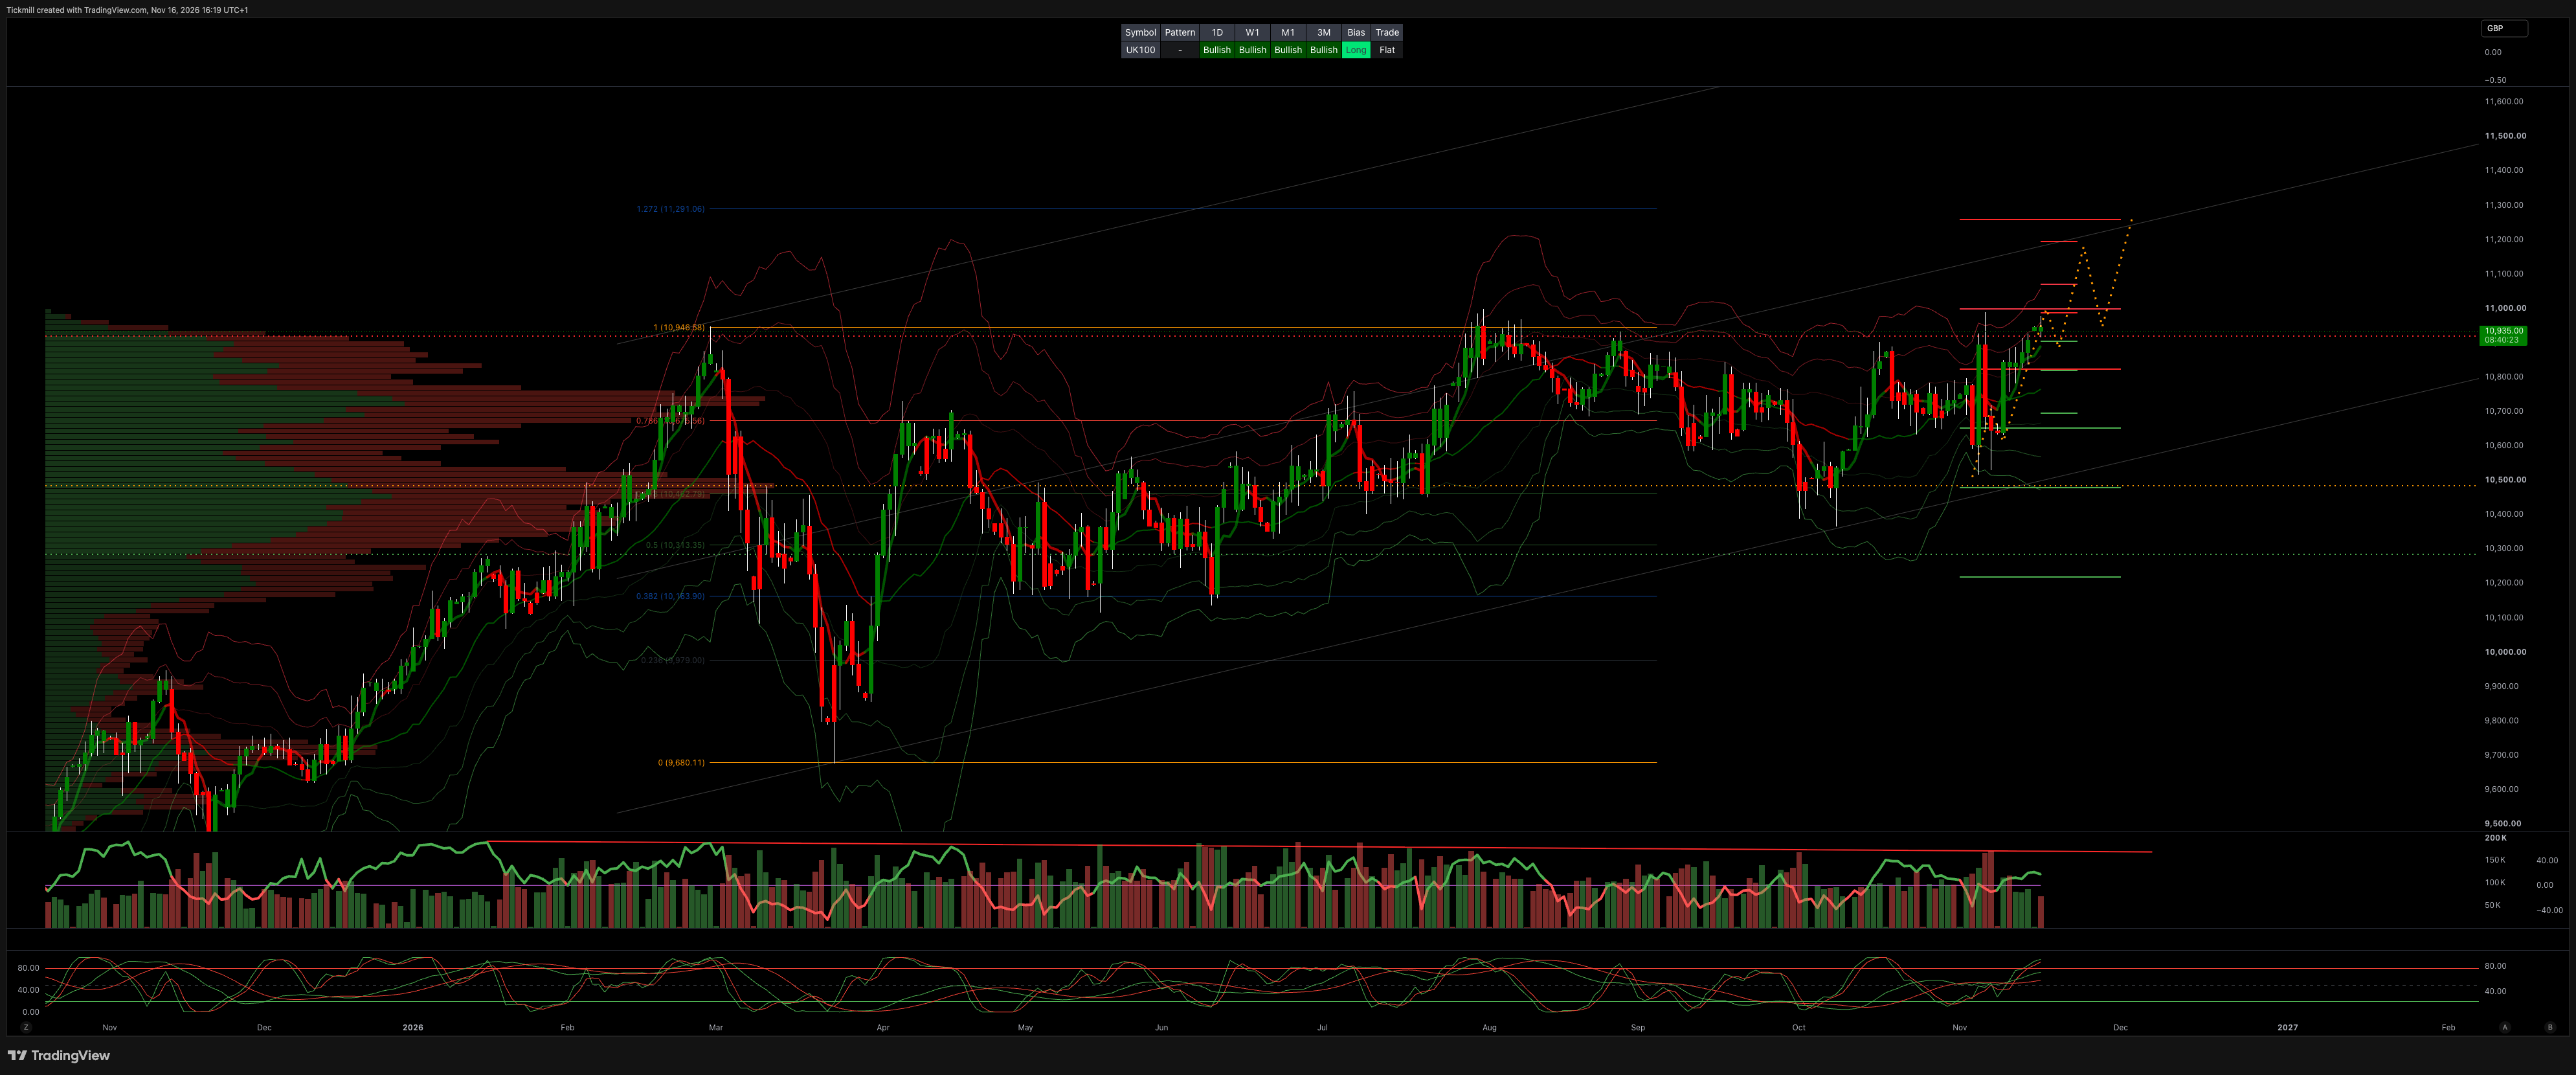
FTSE Climbs to Two-Week Highs as Defence Rally Offsets Mining Drag Ahead of Inflation Data
London's benchmark FTSE 100 gained modest ground on Monday in laboured trading, clawing its way to near two-week highs as aerospace and defence stocks surged on expectations of closer U.K.-EU defence and trade cooperation. The blue-chip index touched an intraday high of 10,962.96 before paring a portion of its gains into the late afternoon to trade around 10,926.46 (+0.22%). Investors tracked corporate updates and weighed hawkish central bank rhetoric while awaiting crucial domestic labour and inflation reports alongside global artificial intelligence catalysts—including Nvidia's upcoming quarterly results and Anthropic's expected market listing—later this week.
Aerospace, defence, and consumer defensive counters led the top-flight risers. Babcock International climbed more than 3%, BAE Systems gained 2.85%, and Melrose Industries moved up 2.5%, while Rolls-Royce Holdings added 1.0% to 1.3% on optimism surrounding potential U.K.-EU summit agreements. Consumer staples and speciality chemicals also drew solid demand, with Coca-Cola HBC advancing 2.1% and Croda International rising 1.8%. Broad-based gains between 1.0% and 1.3% were logged across Metlen Energy & Metals, JD Sports Fashion, Marks & Spencer (which hit a fresh 52-week high), British American Tobacco, J Sainsbury, Prudential, Haleon, Reckitt Benckiser, and GSK. Outsourcing specialist Bunzl advanced 1.05% after initiating the second tranche of its share buyback programme.
Conversely, falling industrial and precious metal prices weighed on resource heavyweights, while rate-sensitive sectors faced pressure. Copper and gold prices softened—with spot gold hitting its lowest level in over a year—dragging Anglo American Plc, Rio Tinto, Fresnillo, Endeavour Mining, and Antofagasta down between 1.0% and 1.4%. Financial and utility stocks also lagged: Legal & General dropped 2.1% despite reporting continued third-quarter growth across its retirement and retail divisions, while IG Group Holdings and Centrica drifted lower by 2.3% and 2.1%, respectively. Pullbacks of 1.0% to 1.4% hit Barratt Redrow, Polar Capital Technology Trust, and United Utilities. Outside the top flight, industrial property group Sirius Real Estate fell over 2% after reporting a sharp drop in first-half earnings due to higher finance costs and a valuation deficit.
On the monetary policy and macroeconomic front, hawkish Bank of England commentary kept upward pressure on front-end sovereign bond yields. Following weekend remarks from BoE Chief Economist Huw Pill signalling that further rate hikes may be needed and that market pricing for additional tightening over the next year is "not outrageous," two-year U.K. Gilt yields climbed above 5%, their highest level since October 2023.
Looking ahead, the U.K. economic calendar delivers two pivotal policy catalysts over the next 48 hours. Tuesday brings the U.K. official labour market report, followed on Wednesday by the October Consumer Price Index (CPI) release. With the BoE forecasting annual inflation at 3.7% and Governor Andrew Bailey scheduled to speak on Wednesday, an upside inflation surprise could prompt money markets to rapidly bring forward expectations for the next rate hike from February to as early as the December MPC meeting.
Finish Line: U.K. equities started the week strongly, moving back toward record closing levels as defence sector momentum and consumer staples resilience offset weakness across miners and rate-sensitive financials. With two-year Gilt yields topping 5% on hawkish BoE signals, market conviction remains measured ahead of tomorrow’s jobs data and Wednesday’s decisive October CPI print.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!